A clear breakdown of the extra expenses that show up when you buy a car, including dealer doc fees, sales tax, registration, financing charges, and insurance...
Most people don’t dread the test drive. They dread the financing office. And I get it. Auto loans come with a whole new language: APR, term length, pre-approval, add-ons, and a stack of paperwork that can make your eyes glaze over.
Let’s slow it down and make it practical. By the end of this guide, you’ll understand how a car loan actually works, what you can control, what you should watch for, and how to walk onto the lot already knowing your numbers.
Car loan basics (no jargon)
An auto loan is just money you borrow to buy a vehicle, paid back over time with interest. The vehicle itself is the collateral, meaning if payments stop, the lender can repossess it.
The four numbers that matter most
- Vehicle price: What you and the seller agree the car costs.
- Down payment: Money you pay upfront, reducing how much you borrow.
- Loan term: How long you take to pay it back, usually 24 to 84 months.
- APR: A standardized annual disclosure of the cost of credit. It often tracks closely to your interest rate, but can include certain finance charges depending on the loan and lender.
Your monthly payment is mainly a function of how much you borrow, your APR, and your term length.
APR vs interest rate
People use “interest rate” and “APR” interchangeably, but they are not always identical. The interest rate is the rate used to calculate interest on your balance. APR is a standardized way to express the cost of borrowing per year and may include certain finance charges. It usually does not include things like sales tax, title, registration, or most non-lender fees, even if you roll them into the amount financed.
For shoppers, the key move is simple: compare offers using APR on the same term length. A low APR on a longer term can still cost you more in total interest than a slightly higher APR on a shorter term.
Total cost beats monthly payment
Dealers and lenders often focus on monthly payments because it’s easy to make a deal look cheaper by stretching the term. Always ask:
- What is the APR?
- What is the finance charge? (This is the cost of the loan itself.)
- What is the total of payments? (This is the total amount you’ll pay back: principal plus finance charge.)
- Is there a prepayment penalty? (Many auto loans have none, but confirm.)
Loan term length
Longer terms lower the monthly payment, but they usually increase the total interest you pay. They also raise your chances of becoming “upside down”, meaning you owe more than the car is worth.
Typical term tradeoffs
- 36 to 48 months: Higher payments, less interest, you build equity faster.
- 60 months: Common sweet spot for many buyers, depending on rate and budget.
- 72 to 84 months: Lowest payments, but often the most expensive overall and the riskiest for negative equity.
A quick example
Let’s say you finance $25,000.
- 60 months at 6% APR costs less in total interest than 84 months at 6% APR, even though the 84-month payment is lower.
- That lower payment comes with a trade: you pay interest for more months, and you stay in the “I owe more than it’s worth” zone longer.
If you’re considering 72 or 84 months just to make the payment work, that’s usually a sign the car is out of budget. A cheaper trim, a used option, or a higher down payment tends to be the healthier fix.
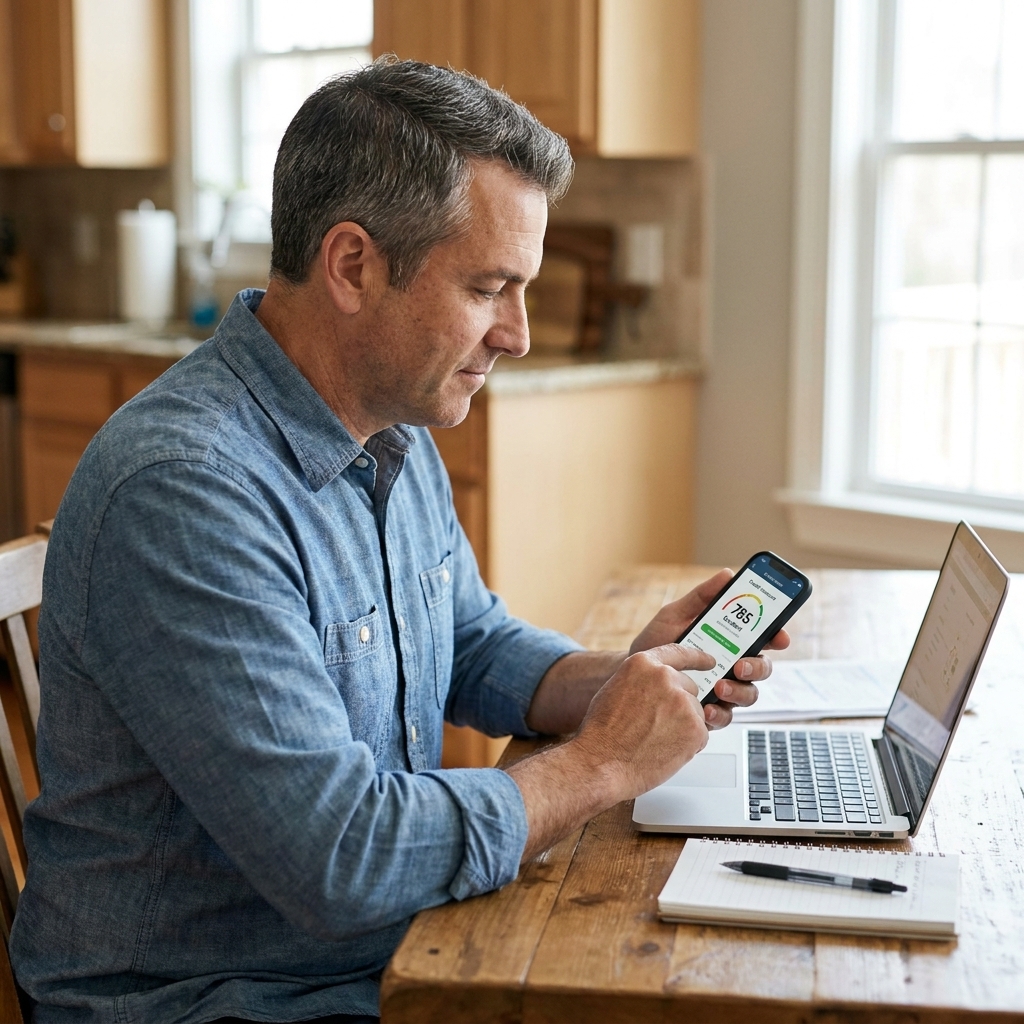
Credit scores and your rate
Your credit profile helps lenders estimate risk. In plain English: the stronger your credit, the more likely you are to get approved and the lower the APR tends to be.
What lenders look at
- Payment history: Late payments hurt. Consistent on-time payments help.
- Debt-to-income ratio (DTI): If your monthly debts are already heavy, approval can be harder.
- Credit utilization: Maxed-out cards can drag your score down.
- Credit age and mix: A longer, stable history helps.
Two quick tips that can genuinely move the needle before you apply:
- Pay down revolving debt (credit cards) if you can, even a little.
- Check your credit reports for errors and dispute anything incorrect.
Down payment, trade-in, and taxes
The amount you finance is not always the sticker price. Your loan amount is usually based on the out-the-door cost, minus your down payment and any trade-in credit.
What increases the amount you finance
- Sales tax, title, registration, documentation fees
- Add-ons like extended warranties, GAP, accessories, paint protection
- Negative equity from your current car loan (rolling old debt into the new loan)
What reduces the amount you finance
- Down payment
- Trade-in value (minus any payoff owed)
- Manufacturer rebates or incentives (if applicable)
One more number: LTV
Lenders also look at loan-to-value (LTV), basically how much you’re borrowing compared to the car’s value. Zero down plus taxes, fees, and add-ons can push your LTV high enough to trigger a higher rate, require a bigger down payment, or cause a denial.
If you want the cleanest deal, focus on out-the-door price first, then financing. Mixing the two conversations is how people accidentally overpay.
Pre-approval
If I could give every first-time buyer one piece of advice, it’s this: get pre-approved before you shop. Pre-approval means a lender reviews your basic info and credit and gives you a conditional offer.
Some pre-approvals come with a specific rate. Others give a rate range. Either way, the final rate and approval can depend on details like the vehicle (new vs used), the loan term, the amount you finance, and verification of your income and identity.
Why pre-approval helps
- You know your budget in real numbers, not guesses.
- You can negotiate the car price without getting distracted by monthly payment games.
- You can compare the dealer’s offer to your own lender’s offer.
Where to get pre-approved
- Credit unions (often very competitive)
- Banks
- Online lenders and marketplaces
- Some automakers offer financing, but compare it like any other offer
Bring your pre-approval terms with you. A dealership may still beat it, and that can be a win. The point is you’re no longer negotiating blind.
Dealer financing vs your own lender
Dealerships can arrange financing through banks and captive lenders (the automaker’s finance arm). That convenience can be great, but you should understand how the money flows.
What can happen in the finance office
- The dealer submits your application to multiple lenders.
- A lender approves you at a certain rate based on their criteria.
- Depending on the lender, the program, and state rules, the dealer may be allowed to mark up the approved rate and keep part of the difference as profit (often called dealer reserve).
This doesn’t mean dealer financing is bad. It means you should shop rates first so you can spot a great offer versus an expensive one, and ask for a better rate if you think there’s room.
Questions I recommend asking
- What is the APR, and is it the best you can do today?
- Is there any discount for automatic payments?
- Can you show me the breakdown of the amount financed?
- Is this loan simple interest, and are there any prepayment penalties?
New vs used matters
Rates and eligibility can differ for new vs used vehicles. Many lenders charge higher APRs for older cars, higher mileage, or certain model years, and some limit the maximum term on used vehicles.
Common add-ons
The finance office is where a lot of profit is made on products, not just the loan. Some add-ons can be useful. Some are overpriced. Most are optional.
GAP insurance
GAP helps cover the difference if your car is totaled and you owe more than the insurance payout. It can be valuable if you have a small down payment, a long term, or you’re rolling negative equity.
Tip: compare GAP pricing through your auto insurer too. Sometimes it’s cheaper there.
Extended warranty (service contract)
These can make sense on certain vehicles, especially high-tech models where repairs are expensive. But pricing varies a lot.
- Ask what’s covered and what’s excluded.
- Ask whether you can cancel and get a prorated refund.
- Never let the warranty conversation distract you from the APR and total loan cost.
Extras like paint protection, etching, fabric guard
Not automatically useless, but often high-margin. If you want them, negotiate the price or consider aftermarket options.
One practical rule: if someone tells you an add-on is “required,” ask them to show you where it’s required in writing. Legit requirements exist (like insurance coverage levels), but many products are simply optional.
Compare loan offers
If you’re looking at multiple offers, compare them apples-to-apples. Here’s a simple checklist that works.
- Same term length (60 vs 60, not 60 vs 72)
- APR
- Finance charge (cost of borrowing)
- Total of payments (total paid over the life of the loan)
- Amount financed (watch for rolled-in add-ons)
- Prepayment penalty (prefer none)
- Required insurance or products (be cautious if something feels mandatory)
And one more that’s not on paper: comfort level. If someone won’t answer clear questions or keeps redirecting you to monthly payment only, that’s a sign to slow down.
Smart financing steps
- Set a realistic budget based on your monthly income and existing debts.
- Estimate total ownership costs like insurance, fuel, charging, maintenance, and registration.
- Check your credit and clean up any issues you can.
- Get pre-approved from at least one lender.
- Shop the car and negotiate price based on out-the-door cost.
- Compare financing options between your pre-approval and the dealer’s best offer.
- Review the contract carefully before signing. Verify APR, term, amount financed, and any add-ons.
- Pay attention to simple interest. Paying earlier in the month can reduce interest over time, and paying late can increase it.
- Make an early principal payment when possible if there’s no prepayment penalty. It can reduce total interest.
Quick FAQ
What credit score do I need for a car loan?
There’s no single cutoff. People get approved across a wide range of scores, but stronger credit usually means better APR and easier approval. If your credit is thin or rebuilding, a credit union or a co-signer can sometimes help, but only if the payment is truly affordable.
Is it better to put money down or take a lower APR?
Ideally you want both, but if you have to prioritize, compare the math. A down payment reduces the amount you borrow and can help you avoid being upside down. A lower APR reduces interest cost over time. If your down payment helps you qualify for a better APR tier, that can be a double win.
Should I choose 72 or 84 months to get a lower payment?
Only if you’re confident you’ll keep the car long-term and the rate is still competitive. Long terms can trap you in negative equity if you need to sell or trade early.
Does getting pre-approved hurt my credit?
Pre-approval often involves a credit check. Many scoring models treat multiple auto loan inquiries within a rate-shopping window as a single event, but the window varies by model and can be roughly 14 to 45 days. If you’re rate shopping, do it in a tight window and ask lenders whether they use a hard inquiry.
Can I refinance later?
Often, yes. If your credit improves or rates drop, refinancing can lower your APR or payment. Just watch fees and make sure the new term doesn’t extend the loan so far that it increases total cost.
Is a co-signer a good idea?
A co-signer can help you qualify or get a better rate, but it’s a serious commitment. If you miss payments, it can hurt their credit too, and they’re legally responsible for the debt. Only use a co-signer if the payment is comfortably affordable and you have a clear plan to refinance on your own later.
What paperwork matters most before I sign?
Read the Truth in Lending disclosures and the retail installment contract carefully. Confirm the APR, finance charge, total of payments, term length, amount financed, and that any optional products you said no to are actually removed.
My bottom line
A car loan isn’t just a monthly payment. It’s a contract that can follow you for years. The good news is you can control a lot of it: shop your rate, get pre-approved, keep the term reasonable, and stay focused on out-the-door price and total cost.
If you walk into a dealership already knowing your APR range and your maximum comfortable payment, you’re no longer guessing. You’re just a buyer making a smart decision, which is exactly how it should be.